Tuesday, March 18, 2014

5 Reasons to Buy Now

Based on prices, mortgage rates and soaring rents, there may have never been a better time in real estate history to purchase a home than right now. Here are five major reasons purchasers should consider buying.

1. Competition is about to Increase

Every spring a surge of prospective purchasers enter the housing market. Like you, they will want the best home available in the best location at the best price. They will be competing with you for the ‘steals’ in the market. Don’t miss the opportunity to get that ‘once-in-a-lifetime’ buy available today that no longer be available as the market heats up..

2. Price Increases Are on the Horizon

Nationally, home prices are projected to appreciate by 4.5% in 2014 and by over 19% from now until 2018. First home buyers will probably pay more both in price and interest rate if they wait until the spring. Even if you are a move-up buyer, it will wind-up costing you more in net dollars as the home you will buy will appreciate at approximately the same rate as the house you are in now.

3. Owning a Home Helps Create Family Wealth

Whether you rent or you own the home you are living in, you are paying a mortgage. Either you are paying your mortgage or your landlord’s. The Federal Reserve, in a recent study, revealed that the net worth of the average homeowner is 30 times greater than that of a renter.

4. Interest Rates Are Projected to Rise

The Mortgage Bankers Association, the National Association of Realtors, Freddie Mac and Fannie Mae have all projected that the 30-year mortgage interest rate will be over 5% by the spring of 2015. That is an increase of almost 3/4 of a point over current rates.

5. Buy Low, Sell High

Most would all agree that, when investing, we want to buy at the lowest price possible and hope to sell at the highest price. Housing can create family wealth as long as we follow this simple principle. Today, real estate is selling ‘low’ compared to where it will be next year. It’s time to buy.

Courtesy of KCM Blog

Monday, March 17, 2014

Happy St. Patrick's Day

I saw this in front of a house on the way out to Kuna today.  How festive!

Saturday, March 15, 2014

The Eagle Has Landed!

I have seen some unusual and large lawn ornaments but take a look at this one!

Friday, March 14, 2014

Lovely Home located in Eagle's Brookwood

Give me a call to take a look at this brand new listing, priced at $316,000. For more information and photos you can go to my website:  LowesFlatFee.com.

Thursday, March 13, 2014

Mortgage Credit Availability Eases

Please make sure and note the difference between the estimated availability in 2006 and now, amazing!

WASHINGTON, D.C. (March 11, 2014) — Mortgage credit availability increased slightly in February according to the Mortgage Credit Availability Index (MCAI), a report from the Mortgage Bankers Association (MBA) which analyzes data from the AllRegs® Market Clarity® product.

"For the third month in a row, mortgage lenders and investors slightly expanded credit offerings in February on net, as a result of offsetting factors,” said Mike Fratantoni, MBA’s Chief Economist.  "Specifically, the recently implemented QM/ATR sections of the new CFPB regulations stipulate that ARM loans must qualify at the highest allowable rate for the first five years of the loan.  As a result, many investors have discontinued loans whose interest rate adjusts after only 3 year (also known as 3/1 ARMS).  While there was significant pull-back on these 3/1 programs, lenders and investors added several new 5+ year ARM programs, including those for Jumbo loans, to their repertoire resulting in a net increase to the MCAI.”


Source: Mortgage Bankers Association; Powered by AllRegs® Market Clarity®

The MCAI increased 0.44 percent from 113.0 in January to 113.5 in February.  A decline in the MCAI indicates that lending standards are tightening, while increases in the index are indicative of a loosening of credit.  The index was benchmarked to 100 in March 2012.  If the MCAI had been tracked in 2007, it would have been at a level of roughly 800, indicating the credit was much more available at that time.


Source: Mortgage Bankers Association; Powered by AllRegs® Market Clarity®

ABOUT THE MORTGAGE CREDIT AVAILABILITY INDEX
The MCAI provides the only standardized quantitative index that is solely focused on mortgage credit.

The MCAI is calculated using several factors related to borrower eligibility (credit score, loan type, loan-to-value ratio, etc.).  These metrics and underwriting criteria for over 85 lenders/investors are combined by MBA using data made available via the AllRegs® Market Clarity® product and a proprietary formula derived by MBA to calculate the MCAI, a summary measure which indicates the availability of mortgage credit at a point in time.  Base period and value for all indexes is March 31, 2012=100.


Wednesday, March 12, 2014

February Market Report…kind of like skiing in the rain. It’s good but you wish it was better.

by Marc Lebowitz, RCE, CAE

ACAR Executive Director

Single family home sales in February 2014 were 422 in Ada County, an decrease of 10% compared to February 2013.  January sales were strong, and, when linked with February gives us a YTD total sales exactly equal to this time last yea; 836 homes sold.

In February more than 50% of our total sales were for homes priced above $160,000.  Sales of homes priced above $160,000 were up over February 2013.

Days on Market for February were 66.  That’s down from February, but still up significantly from December’s 59. In February 2013, Days on Market was 72.

New homes sold in February totaled 96; down 9% from last year.

Existing home sales were 326; down 10%.

Historically, February sales increase from January by an average of 3%. February 2014 posted a 4% increase over January.

Of the total sales in February, 13% were distressed; up 1% from last month. In February 2013, 23% of sales were distressed.

For the month of February, REO sales (62% of Distressed; 34 total sales) exceeded Short Sales (38% of Distressed; 20 total sales).

Pending sales at the end of February were 951; down 10% from February 2013.

Of Pending sales in distress (12%), there are slightly more Short Sales (57%; 65 sales) than REO’s (43%; 49 sales).

February median home price was $199,650; up 11% from February 2013.

New Homes median price for February was $320,500; up 23% from February 2013. For Existing homes the increase is 6% to $169,900.

The number of houses available for sale at the end of February increased  slightly from January 2014 to 2,127.  This reverses four consecutive month of decrease.  This is 23% more than last year at this time…which we need heading into Spring.

We anticipate continued inventory growth from now until the end of Summer.

Of the total active listings, 10% are distressed, down 1% from January.

Of our Distressed Inventory, 67% is Short Sales (142) and 33% is REO (70).

In Ada County we now have 4.7 months of inventory on hand, up a little from the end of January.

The price category in shortest supply is <$100K where we have 1.4 months.

From $100,000 to $119,000 we have 2.1 months available.

From $120,000 to $160,000 we have just under 3 months available inventory.

From $160,000 to $300,000 we have nearly 5 months…except for the very popular $250,000 – $300,000 which has only 4.5 month’s supply available.

Above $300,000 we have a 5 month’s supply. Above $500,000 the supply is closer to 14 months.  Remembering that 6 months of available inventory describes a “stable real estate market”; it looks like we are heading into a period of “normal” like we haven’t seen in several years.

Of sales in February, the most popular price point was $120,000 to $160,000 (26%); followed by $160,000 to $200,000 (14%) and  $200,000 to $250,000 with 12%.

So…what’s next?

Sales did hit a Winter wall in February.  We are now chasing a super strong Spring and Summer 2013. March 2013 sales were 550.  Can we increase sales from 422 to 550 with Pending sales where they are? It’s going to be close.

February is typically our weakest month for median home price. February 2014 was pretty strong.  This should continue into the Summer.

We are seeing more and more data that says that the Millennials (the big homebuyer wild card) are feeling better and better about home ownership.  Nearly 90% of Millennial buyers say “homeownership is a good investment”.

This is the pent up demand we’ve been waiting to see activate.

Bottom line…its going to be a complicated first quarter for real estate.


Saturday, March 8, 2014

How to Price Real Estate

An excellent analogy on home pricing from KCM Blog:


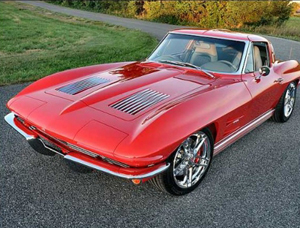
1963 Chevrolet CorvetteLocation may have the most effect on value but Price is without question the most important factor controlling the sale of real estate.  Anything will sell anytime, how long will it take depends on the price.

Think about it this way – you may really want to buy a car for your collection and your favorite happens to be a 1963 Corvette.  So you hear about one for sale, in mint condition, across town but the only problem is the price, the owner is asking $150,000!  Well, although you really, really want a mint condition 1963 Corvette, there is no way you will pay anywhere close to $150,000, in fact you know that the most a 1963 Corvette has ever sold for is about $200,000 and that was for a very rare model, which this one is not.

Because you are a bit obsessed with owning one of these cars you spend almost all of your free time, and some of the time you should be working, searching the internet for available cars.  Through this exhaustive search you have become somewhat of an expert on the values of 1963 Corvettes, especially in your town.  You happen to know that the particular model for sale across town is worth about $95,000…maybe $100,000.  In fact, if the asking price was $100,000 or even $110,000 you would’ve driven over there today with your checkbook and driven home in a 1963 Corvette!

So why don’t you go make an offer? Well, let’s face it when you see a price that is so high compared to the actual value it makes you think that the seller is either difficult to deal with and is out of touch with reality or that he must not really want to sell the car, instead he is just fishing for the one fool in the world that will pay $150,000 for a car that is worth $95,000.  So you don’t even go look at it or call for more information…you just keep searching the various websites to find the car of your dreams.

Yes, you guessed it the Corvette in this example actually represents your home or other real estate you might be trying to sell.  (in fact it represents any item that can be bought and sold).

Wiggle room = Bad idea


Most sellers think that it is necessary to “leave a little wiggle room” in the price.  They think this because they think that all buyers will make aggressively low offers…no matter what the asking price.  WRONG!!

Buyers pay the fair market value …in other words they will pay you what it is worth!  Your job is to find out what it is worth and price it at or near that value.

This is where brokers and/or appraisers come into the picture.  The right way to price your property is to have a professional REALTOR/broker or appraiser prepare a CMA (Comparative Market Analysis) on your property.  A CMA involves finding recent sales of similar properties, adjusting for any differences, to arrive at a current market value of your property.  Once you have this value you should have your broker set the asking price no more than 3% to 5% higher than that current market value.

If you do this, your property will sell quickly for a price equal to exactly what it is worth, or higher!   Buyers as a general rule DO NOT make “low-ball” offers, there are some rare occasions when that happens but the vast majority of initial offers are 5% or less below asking price.

If sellers price their property correctly the buyers will know it immediately because, just like in the Corvette example, buyers spend every spare moment searching the internet for a home, they have made themselves experts on the market value of the particular type of home in the particular area they desire.  For this reason the buyer also knows when a property is overpriced.  Most buyers will not even go look at a property that is overpriced, they say to themselves “why bother?” they assume that the seller is unreasonable and/or is not truly interested in selling the property.

Yesterday, the Buyer’s Specialist that works for my team and I were showing a house to some buyers who were very motivated had already decided on the neighborhood.  The house was well within their price range and met every one of their criteria.  As we stood in the kitchen discussing what price we should offer we found ourselves drawn to the fact that the house had been on and off of the market for the last four years!

The conversation immediately turned to “what is wrong with this house?”   It turns out that the house hasn’t sold because it was severely overpriced most of that 4 years, it happens to be well priced now but the stigma it carries because of the lengthy time on the market will likely result in it selling for less than it is really worth.

Moral of this whole story is - buyers will pay what it is worth - Seller’s job is to find out what it is worth and set the asking price 3%-5% higher than that number…then sit and wait for the offers to roll in.